
Market Overview
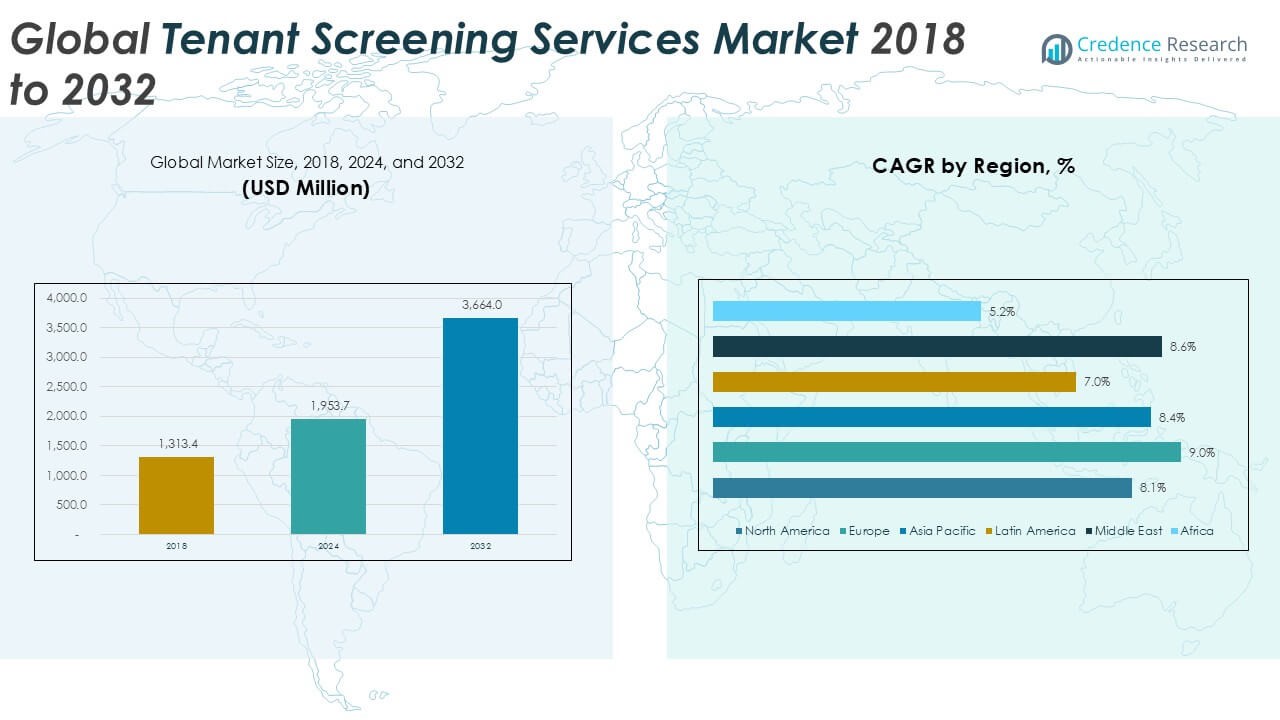
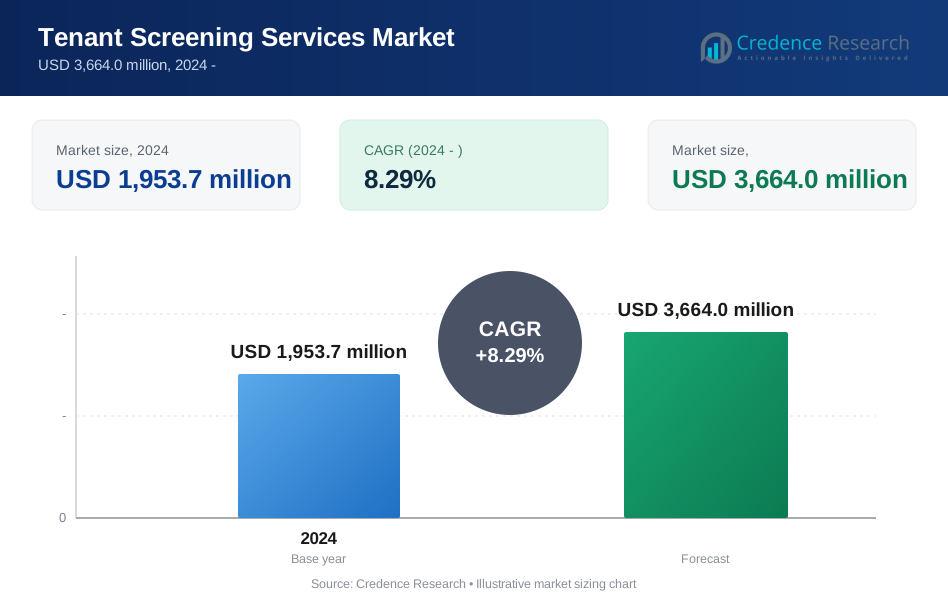
The Tenant Screening Services market size was valued at USD 1,313.4 million in 2018 and USD 1,953.7 million in 2024, and is anticipated to reach USD 3,664.0 million by 2032, at a CAGR of 8.29% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Tenant Screening Services Market Size 2024 | USD 1,953.7 Million |
| Tenant Screening Services Market, CAGR | 8.29% |
| Tenant Screening Services Market Size 2032 | USD 3,664.0 Million |
The Tenant Screening Services market is dominated by established players such as TransUnion, Experian, Equifax, and CoreLogic, which hold a significant share due to their extensive databases, advanced analytics capabilities, and strong brand recognition. These companies offer integrated solutions covering credit checks, background verification, and rental history assessments, making them preferred partners for large property management firms. Emerging players like RentSpree, TurboTenant, and TenantCloud are gaining traction by offering flexible, cloud-based platforms tailored to small landlords and independent agents. Regionally, Asia Pacific leads the global market, accounting for 31.7% of the total market share in 2024, driven by rapid urbanization, increasing rental demand, and digital transformation in countries like China and India. North America and Europe follow closely, with 27.2% and 24.7% market shares respectively, supported by regulatory compliance and widespread use of structured tenant evaluation processes across rental housing sectors.
Market Insights
- The Tenant Screening Services market was valued at USD 1,953.7 million in 2024 and is projected to reach USD 3,664.0 million by 2032, growing at a CAGR of 8.29% during the forecast period.
- Growth is driven by rising rental housing demand, increasing need for risk mitigation by landlords, and regulatory compliance requirements encouraging structured screening processes.
- Trends include growing adoption of cloud-based platforms, expansion of AI-powered screening tools, and the shift toward mobile-friendly solutions for individual landlords.
- Key players such as TransUnion, Experian, and Equifax dominate the market, while new entrants like TurboTenant and RentSpree are gaining ground through tech-enabled offerings; however, data privacy concerns and lack of standardized databases in some regions limit market expansion.
- Asia Pacific leads with a 31.7% market share in 2024, followed by North America (27.2%) and Europe (24.7%); by segment, Credit Checks and Cloud-based technology remain dominant due to their reliability and scalability.
Market Segmentation Analysis:
By Service Type
The Tenant Screening Services market by service type is led by Credit Checks, accounting for the largest market share in 2024. This dominance is attributed to landlords’ increasing reliance on financial background data to evaluate tenant reliability and mitigate default risks. Credit checks serve as a fundamental screening step, offering insights into payment history, debt levels, and financial behavior. Rising rental defaults and the growing importance of financial trustworthiness in high-demand housing markets continue to drive demand for this service. Additionally, increased automation in report generation has made credit checks faster and more accessible to landlords and agencies.
- For instance, TransUnion SmartMove processed over 3.1 million screening reports in a single year, with credit checks being the most requested service, helping landlords make decisions in under 10 minutes through automated workflows.
By Technology Used
In terms of technology, the Cloud-based segment holds the largest revenue share in 2024 and is projected to maintain its dominance through the forecast period. The growth of cloud-based tenant screening solutions is driven by their scalability, ease of integration, and cost-efficiency for users of all sizes. Property managers and landlords increasingly prefer cloud-based platforms due to their ability to access real-time data, automate verification processes, and ensure regulatory compliance across multiple properties. The increasing digital transformation of the real estate sector further supports the adoption of cloud-based technologies over traditional on-premises systems.
- For instance, AppFolio Property Manager, a cloud-based solution, supported 17,500+ real estate customers with tenant screening tools embedded in its platform, processing over 1.5 million screening requests through its integrated system in the past year.
By End User
Among end users, Property Management Companies emerged as the dominant segment in 2024, holding the highest market share. This leadership position is driven by their widespread use of comprehensive tenant screening services across diverse residential and commercial property portfolios. These companies prioritize efficiency and risk minimization, making tenant verification processes such as credit, income, and rental history checks essential. Their reliance on technology-enabled screening platforms supports consistent decision-making and tenant quality. Additionally, growing urbanization and the expansion of professionally managed rental properties further fuel the demand for robust tenant screening among property management firms.
Key Growth Drivers
Rising Rental Housing Demand
The global surge in urbanization and housing affordability challenges has significantly increased demand for rental properties, thereby boosting the need for tenant screening services. As rental markets expand, landlords and property managers are prioritizing reliable tenant selection to reduce risks associated with non-payment, property damage, or legal disputes. This shift towards structured and data-driven rental decisions has accelerated the adoption of professional screening solutions, particularly in urban centers and multi-family housing developments. The growth of short-term rentals has also contributed to the broader usage of screening services.
- For instance, TurboTenant, a platform serving small landlords, experienced growth to 550,000+ active landlords, with over 5 million tenant applications screened as of the latest reporting year, reflecting this rising demand.
Regulatory Compliance and Risk Mitigation
Stricter regulations around fair housing, background checks, and data privacy have prompted landlords and property managers to adopt compliant, standardized tenant screening solutions. These services help mitigate legal risks by ensuring consistent and unbiased application of screening criteria. With increasing awareness of tenant rights and data protection laws, professional services offer structured workflows that align with compliance requirements. Moreover, tenant screening platforms help minimize financial losses by identifying high-risk applicants, which is particularly critical for large-scale property owners and institutional landlords operating across jurisdictions.
- For instance, First Advantage maintains operations in over 30 countries, processes 71 million background checks annually, and has built automated compliance frameworks that align with both FCRA and GDPR standards, helping multinational clients manage tenant risks legally and efficiently.
Digital Transformation of Property Management
The integration of digital tools in real estate management has accelerated the use of automated tenant screening services. Landlords and agencies are increasingly adopting cloud-based platforms that enable faster, more accurate, and remote verification processes. These technologies offer user-friendly interfaces, data analytics, and integration with listing platforms and property management software, creating a seamless end-to-end solution. Digitalization also improves operational efficiency, scalability, and customer experience. As tech-savvy landlords and tenants seek convenience and speed, the digital transformation continues to act as a strong growth catalyst in the tenant screening services market.
Key Trends & Opportunities
AI-Powered Screening Tools
Artificial intelligence and machine learning are transforming tenant screening by enabling more nuanced risk assessments and fraud detection. AI tools analyze vast datasets including behavioral patterns, financial history, and rental behavior, improving accuracy in tenant evaluations. This technology also supports predictive scoring models that offer landlords deeper insights into a tenant’s future reliability. The growing interest in data-driven decision-making, coupled with the need for speed and compliance, creates a significant opportunity for AI-powered platforms to gain market share and set new standards in screening services.
- For instance, Checkr, which specializes in AI-driven background checks, completed more than 30 million screenings in a single year using AI to flag potential risks and streamline turnaround time to under 24 hours for 90% of its screenings.
Expansion of DIY and Mobile Platforms
An increasing number of landlords, especially small property owners, are adopting do-it-yourself (DIY) and mobile-friendly tenant screening solutions. These platforms offer ease of use, quick report generation, and affordability. With mobile apps and digital onboarding tools, landlords can screen tenants remotely, aligning with modern tenant expectations for digital interactions. This trend is driving growth in flexible, subscription-based screening services targeted at individual property owners, creating new market opportunities outside traditional institutional user bases.
- For instance, RentSpree, a mobile-compatible DIY platform, has partnered with over 250 MLSs and Realtor associations and processed over 2 million applications, positioning itself as a go-to solution for independent landlords seeking simple, mobile-first screening tools.
Key Challenges
Data Privacy and Legal Compliance
Tenant screening services operate in a highly regulated environment, facing challenges related to data privacy laws such as GDPR, FCRA, and other local legislation. Non-compliance can result in legal liabilities and reputational damage. Managing tenant consent, data accuracy, and secure data storage are critical yet complex tasks. As regulations evolve, screening service providers must continuously update their systems and policies, increasing operational costs and legal oversight requirements. Ensuring compliance across multiple jurisdictions remains a persistent challenge for global and regional market players.
Risk of Discrimination and Bias
Despite efforts to standardize screening practices, there remains a concern about potential bias or unintentional discrimination in tenant selection. Algorithms and scoring systems, if not carefully designed, can lead to disparate impacts on protected groups, exposing landlords and screening agencies to legal action. Balancing effective risk assessment with fair housing compliance is a key challenge. Service providers must invest in transparent algorithms, human oversight, and periodic audits to ensure ethical practices, which can complicate product development and increase resource demands.
Limited Access to Verifiable Data
In some regions, the lack of centralized or verifiable databases on tenant behavior, income, or employment history limits the effectiveness of screening tools. Small landlords and agencies may struggle to access comprehensive data due to fragmented reporting systems or privacy restrictions. Inconsistent or outdated data sources can lead to inaccurate assessments, increasing the risk of rental defaults or disputes. Overcoming this challenge requires strategic partnerships with financial institutions, credit bureaus, and employment databases, which can be difficult to establish and maintain.
Regional Analysis
North America
North America held a significant share of the Tenant Screening Services market in 2024, valued at USD 531.49 million, up from USD 361.96 million in 2018, and is projected to reach USD 979.37 million by 2032, registering a CAGR of 8.1%. The region accounted for approximately 27.2% of the global market in 2024. This growth is driven by a mature rental housing sector, widespread adoption of digital screening tools, and strict tenant verification regulations. High landlord awareness regarding risk mitigation and financial assessments continues to fuel demand, especially across the United States and Canada.
Europe
Europe represented about 24.7% of the global Tenant Screening Services market in 2024, with a valuation of USD 481.95 million, rising from USD 310.87 million in 2018, and projected to reach USD 952.63 million by 2032, at a CAGR of 9.0%. This robust growth is supported by increased professionalization of the rental market and stricter compliance with tenant rights and data protection laws. European landlords and agencies are adopting standardized screening protocols and leveraging digital platforms to meet evolving regulatory standards, particularly in the UK, Germany, and France.
Asia Pacific
Asia Pacific dominated the global Tenant Screening Services market in 2024 with the highest regional share of 31.7%, valued at USD 619.04 million, up from USD 413.05 million in 2018, and forecasted to reach USD 1,172.46 million by 2032, growing at a CAGR of 8.4%. Rapid urbanization, a growing middle class, and increasing cross-border migration have intensified rental housing demand, particularly in countries like China, India, and Australia. This has driven landlords and property firms to invest in efficient, scalable tenant screening solutions to reduce risk and improve tenant quality.
Latin America
Latin America accounted for around 9.5% of the global Tenant Screening Services market in 2024, with market size reaching USD 186.58 million, up from USD 134.09 million in 2018, and projected to hit USD 317.66 million by 2032 at a CAGR of 7.0%. The growth is primarily fueled by increased activity in urban real estate markets in Brazil, Mexico, and Chile, where rental housing demand is on the rise. Although adoption rates are relatively lower compared to developed markets, growing awareness about tenant verification and risk management is gradually improving market penetration.
Middle East
The Middle East Tenant Screening Services market reached USD 95.23 million in 2024, up from USD 62.78 million in 2018, and is anticipated to reach USD 183.20 million by 2032, expanding at a CAGR of 8.6%. The region held approximately 4.9% of the global market share in 2024. Demand is increasing due to expanding rental housing in urban centers such as Dubai, Riyadh, and Doha. As more expatriates and international tenants enter the market, property managers are adopting screening tools to ensure tenant reliability and support regulatory transparency.
Africa
Africa contributed the smallest share to the global Tenant Screening Services market in 2024, with a market size of USD 39.41 million, up from USD 30.60 million in 2018, and forecasted to reach USD 58.62 million by 2032, growing at a CAGR of 5.2%. The region held just 2.0% of the market in 2024. Limited awareness, infrastructure gaps, and informal rental arrangements constrain growth. However, rising urbanization and property investment in South Africa, Nigeria, and Kenya are gradually creating opportunities for structured tenant screening services across both residential and commercial segments.
Market Segmentations:
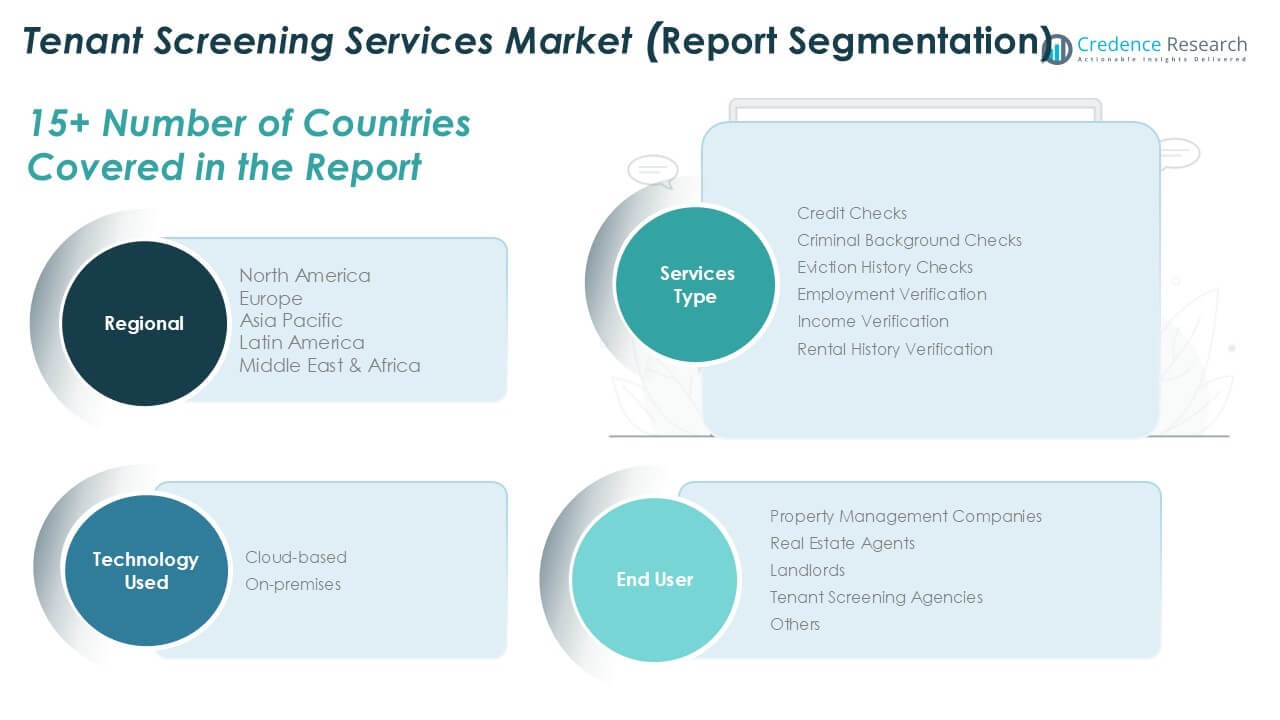
By Service Type
- Credit Checks
- Criminal Background Checks
- Eviction History Checks
- Employment Verification
- Income Verification
- Rental History Verification
By Technology Used
- Cloud-based
- On-premises
By End User
- Property Management Companies
- Real Estate Agents
- Landlords
- Tenant Screening Agencies
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Tenant Screening Services market features a moderately consolidated competitive landscape, with key players such as TransUnion, Experian, Equifax, and CoreLogic leading the market due to their expansive data capabilities, technological infrastructure, and global presence. These companies offer comprehensive service portfolios, including credit reports, background checks, and rental history verifications, often integrated with digital platforms to enhance user experience. Emerging players like RentSpree, TurboTenant, and Checkr are disrupting the market through cloud-based, mobile-friendly solutions tailored to individual landlords and small property managers. Market competition is fueled by advancements in AI, automation, and predictive analytics, prompting firms to invest in technology upgrades and strategic partnerships. Additionally, data privacy compliance and user-friendly platforms have become crucial differentiators. Mergers, acquisitions, and service diversification remain central to growth strategies, as firms seek to expand customer bases and service reach across residential and commercial segments. Overall, innovation and compliance drive competition in this dynamic market.
Key Player Analysis
- TransUnion
- Experian
- Equifax
- CoreLogic
- First Advantage
- RentSpree
- SmartMove
- TenantCloud
- MyRental
- TurboTenant
- Checkr
- LeaseRunner
- RentPrep
- AppFolio
Recent Developments
- In January 2025, Experian offers tenant screening solutions that leverage credit data, rental history, income, and employment verification to provide landlords with tailored insights. This allows landlords to make informed decisions when selecting tenants. Experian also focuses on providing renters with access to their screening reports, empowering them to review and manage their information.
- In January 2025, Zillow and Experian partnered to offer a comprehensive application process for rentals that includes an Experian credit check and background check.
- In March 2022, the tenant screening market has witnessed considerable traits in latest years, pushed with the aid of improvements in generation, regulatory modifications, and evolving market needs. One of the most notable trends is the integration of synthetic intelligence (AI) and gadget mastering into screening procedures. These technologies allow more accurate and efficient evaluations of potential tenants via reading widespread quantities of records, along with credit score histories, criminal records, and apartment backgrounds. AI-powered systems can expect tenant behavior, assisting landlords make knowledgeable decisions and reduce risks related to leasing properties.
Market Concentration & Characteristics
The Tenant Screening Services Market demonstrates a moderately concentrated structure, led by a few major players such as TransUnion, Experian, and Equifax. These companies hold a strong competitive position due to extensive databases, integrated service offerings, and established client relationships. It exhibits characteristics of steady demand growth, driven by rising rental activity, heightened landlord focus on tenant quality, and growing adoption of automated verification solutions. The market serves both large-scale property management companies and individual landlords, creating a mix of enterprise-level and DIY-focused offerings. Cloud-based platforms and mobile accessibility continue to reshape how services are delivered, particularly for small landlords seeking efficiency and affordability. Technology integration, particularly in AI and analytics, plays a key role in shaping competition and service differentiation. Regulatory compliance and data privacy remain core operational priorities. It reflects a growing reliance on digital, scalable solutions while maintaining sensitivity to regional legal frameworks and varying levels of market maturity.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Technology Used, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The tenant screening services market will continue to grow steadily, driven by the rising global demand for rental housing.
- Digital transformation in property management will enhance the adoption of automated and cloud-based screening solutions.
- AI and machine learning technologies will increasingly power predictive tenant scoring and fraud detection systems.
- Landlords and property managers will rely more on integrated platforms offering end-to-end screening and lease management tools.
- Regulatory compliance and data privacy laws will shape service design and operational strategies across regions.
- Demand for mobile-friendly and self-service screening platforms will rise, especially among independent landlords.
- Expansion into emerging markets will create new growth opportunities as rental markets formalize.
- Strategic partnerships between screening service providers and property listing platforms will become more common.
- Competition will intensify as startups introduce niche and affordable solutions tailored to small-scale users.
- Data accuracy, transparency, and ethical use of tenant information will become key competitive differentiators.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Rental Housing Demand
Urbanization and housing affordability challenges are increasing the demand for rental properties globally, prompting landlords and property managers to adopt tenant screening services to reduce risks associated with non-payment, property damage, and legal disputes.
Regulatory Compliance and Risk Mitigation
Stricter regulations around fair housing, background checks, and data privacy are driving the adoption of standardized, compliant tenant screening solutions, helping landlords minimize legal risks and ensure consistent, unbiased application of screening criteria.
Digital Transformation of Property Management
The integration of digital tools and cloud-based platforms in real estate management is accelerating the adoption of automated tenant screening services, enabling faster, more accurate, and remote verification processes for landlords and agencies.
Adoption of AI-Powered Screening Tools
Artificial intelligence and machine learning are enabling more nuanced risk assessments and fraud detection in tenant screening, improving accuracy and efficiency while supporting predictive scoring models for better tenant reliability insights.
Expansion of DIY and Mobile Platforms
The rise of do-it-yourself and mobile-friendly screening solutions is making tenant screening more accessible and affordable for small landlords and independent property owners, expanding the market beyond traditional institutional users.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Tenant Screening Services Market?
What is the projected growth rate of the Tenant Screening Services Market?
What factors are driving the growth of the Tenant Screening Services Market?
What are the key segments within the Tenant Screening Services Market?
What are some challenges faced by the Tenant Screening Services Market?
Who are the major players in the Tenant Screening Services Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Property Management Companies
- 1.2.2 Real Estate Agents
- 1.2.3 Landlords
- 1.2.4 Tenant Screening Agencies
- 1.2.5 Others
- 1.3 By Service Type
- 1.3.1 Credit Checks
- 1.3.2 Criminal Background Checks
- 1.3.3 Eviction History Checks
- 1.3.4 Employment Verification
- 1.3.5 Income Verification
- 1.3.6 Rental History Verification
- 1.4 By Technology Used
- 1.4.1 Cloud-based
- 1.4.2 On-premises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,953.7 million → 2032: USD 3,664.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Tenant Screening Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Tenant Screening Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Tenant Screening Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Tenant Screening Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Tenant Screening Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Tenant Screening Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Tenant Screening Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Tenant Screening Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,953.7 million → 2032: USD 3,664.0 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Tenant Screening Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Property Management Companies
- 12.3.6.2 Real Estate Agents
- 12.3.6.3 Landlords
- 12.3.6.4 Tenant Screening Agencies
- 12.3.6.5 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Credit Checks
- 12.4.6.2 Criminal Background Checks
- 12.4.6.3 Eviction History Checks
- 12.4.6.4 Employment Verification
- 12.4.6.5 Income Verification
- 12.4.6.6 Rental History Verification
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Technology Used - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Cloud-based
- 12.5.6.2 On-premises
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Tenant Screening Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Tenant Screening Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Tenant Screening Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Tenant Screening Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 TransUnion
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Experian
- 18.4 Equifax
- 18.5 CoreLogic
- 18.6 First Advantage
- 18.7 RentSpree
- 18.8 TurboTenant
- 18.9 Checkr
- 18.10 AppFolio
- 18.11 TenantCloud
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

