
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Injection Molding Machine Market Size 2024 | USD 709.8 Million |
| Injection Molding Machine Market, CAGR | 8.3% |
| Injection Molding Machine Market Size 2032 | USD 1343.27 Million |
Market Overview:
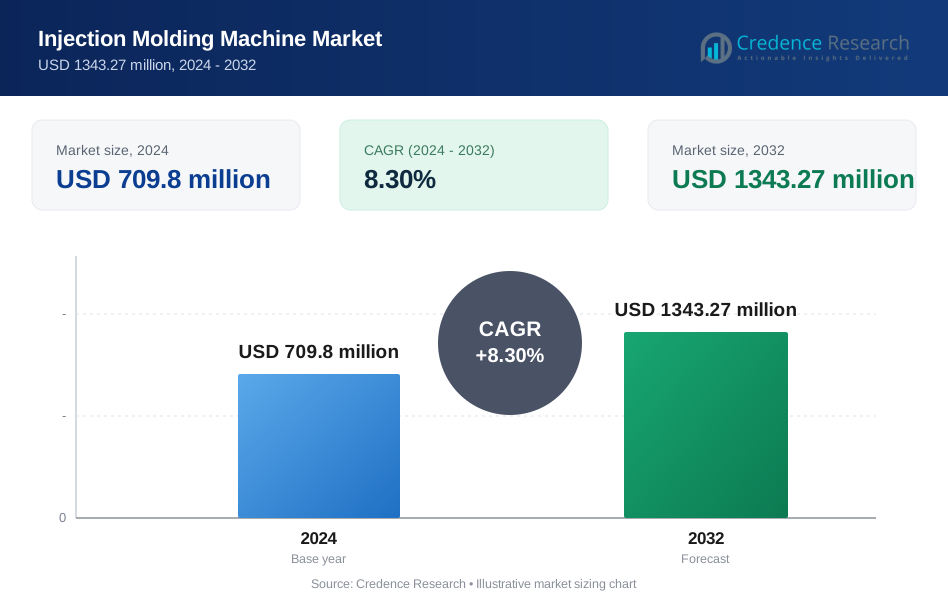
The Injection Molding Machine Market is projected to grow from USD 709.8 million in 2024 to an estimated USD 1343.27 million by 2032, with a compound annual growth rate (CAGR) of 8.3% from 2024 to 2032.
The growth of the injection molding machine market can be attributed to several key drivers. The rapid industrialization in emerging economies, such as China, India, and Brazil, is significantly contributing to the market's expansion. These regions are witnessing a surge in the demand for consumer goods and automotive components, which are frequently manufactured using injection molding technology. The versatility and cost-effectiveness of injection molding make it an ideal solution for producing high volumes of complex, high-precision parts, particularly in sectors like automotive and consumer electronics. Additionally, advancements in automation and the integration of Industry 4.0 technologies, such as AI and IoT, are enhancing the efficiency of injection molding processes. These technologies facilitate predictive maintenance, reduce downtime, and enable the production of more intricate and customized components, thereby boosting market growth.
Geographically, the injection molding machine market is segmented into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Asia Pacific holds the largest market share, with China and Japan being prominent contributors. The presence of a large number of injection molding machine manufacturers and a strong automotive sector in countries like South Korea and India further bolsters the regional market. North America follows closely behind, driven by the automotive, healthcare, and consumer goods industries. The United States is a key player in the region, with a significant number of end-user industries relying on injection molding machines for production. Europe also remains a crucial market, particularly due to the strong automotive and healthcare industries in countries like Germany and France. The Latin American and Middle Eastern regions are expected to experience steady growth, as countries in these areas are increasingly adopting advanced manufacturing technologies to meet the demands of their growing industrial sectors.
Market Insights:
- The injection molding machine market is projected to grow from USD 709.8 million in 2024 to USD 1343.27 million by 2032, with a CAGR of 8.3% from 2024 to 2032.
- Rapid industrialization in emerging economies, like China, India, and Brazil, is significantly contributing to the market's growth, particularly in consumer goods and automotive components.
- Advancements in automation and Industry 4.0 technologies, such as AI and IoT, are improving efficiency, predictive maintenance, and customization in the injection molding process.
- Asia Pacific dominates the market, with China, Japan, and India driving growth due to a strong automotive sector and a large number of manufacturers.
- Increasing demand for lightweight, durable, and high-performance materials in automotive, aerospace, and electronics sectors is boosting the adoption of injection molding.
- Environmental sustainability trends, such as recycling and biodegradable materials, are driving demand for injection molding machines that support eco-friendly practices.
- High initial investment costs, maintenance complexity, and environmental regulations remain challenges, particularly for smaller manufacturers and markets with strict compliance requirements.
Market Drivers:
Technological Advancements in Injection Molding
One of the primary drivers fueling the growth of the injection molding machine market is the continuous advancement in molding technology. The integration of automation and Industry 4.0 solutions, such as artificial intelligence (AI) and the Internet of Things (IoT), has significantly enhanced the capabilities of injection molding machines. These technologies enable real-time monitoring and predictive maintenance, improving efficiency and reducing downtime. For instance, AI-driven process control continuously learns from production data to fine-tune molding parameters, resulting in higher precision and repeatability. As manufacturers continue to seek ways to improve production efficiency and product quality, the adoption of advanced injection molding machines is expected to accelerate.
Increasing Demand for Lightweight and Durable Materials
The demand for lightweight, durable, and high-performance materials is another key driver of the injection molding machine market. In industries such as automotive, aerospace, and consumer electronics, there is an increasing need for components that offer enhanced strength-to-weight ratios. Injection molding enables the production of complex parts with lightweight yet durable materials, such as thermoplastics and composite materials. For example, high-performance polymers like PEEK, PTFE, and PPS offer exceptional heat-resistant properties, making them ideal for automotive, aerospace, and electronics applications. The automotive industry's push for fuel efficiency and the aerospace sector's need for high-strength components are driving the demand for injection-molded parts made from these advanced materials. As these industries continue to prioritize efficiency and performance, the demand for injection molding machines capable of processing such materials is expected to grow.
Growing Industrialization in Emerging Economies
The rapid industrialization in emerging economies, particularly in Asia Pacific, is contributing significantly to the growth of the injection molding machine market. Countries like China, India, and Brazil are seeing substantial increases in their manufacturing output, driven by a growing demand for consumer goods, automotive components, and electronics. The cost-effectiveness and high-volume production capabilities of injection molding make it an attractive option for manufacturers in these regions. As industrialization continues to expand, these emerging markets are increasingly adopting injection molding machines to meet the growing demand for precision-engineered products. This trend is expected to continue, further accelerating market growth.
Environmental Sustainability and Recycling Trends
Environmental sustainability is becoming a crucial factor in the manufacturing process, which is also driving the growth of the injection molding machine market. With growing concerns over plastic waste and resource conservation, industries are focusing on the use of recyclable and biodegradable materials in production. Injection molding machines are capable of efficiently processing such materials, contributing to sustainable manufacturing practices. Additionally, the ability to reuse scrap plastic in the injection molding process helps minimize waste, making it an environmentally friendly production method. As industries, particularly in the automotive and packaging sectors, seek to align with sustainability goals, the demand for injection molding machines that support eco-friendly practices is expected to rise.
Market Trends:
Growth of Hybrid and Electric Injection Molding Machines
One of the prominent trends shaping the injection molding machine market is the increasing adoption of hybrid and electric molding machines. Unlike traditional hydraulic injection molding machines, hybrid and electric machines offer enhanced energy efficiency, reduced operational costs, and lower environmental impact. These machines combine electric motors with hydraulic components to optimize the molding process, offering faster cycle times and improved precision. As industries face increasing pressure to reduce energy consumption and carbon footprints, hybrid and electric injection molding machines are becoming the preferred choice for manufacturers seeking to meet both economic and environmental goals. For example, Sumitomo Heavy Industries Ltd. (SHI) launched the 20-ton iM18E compact hybrid injection molding machine in February 2023, designed for molding electronic parts. This machine offers improved shot-to-shot weight variance and uses 50% less power than comparable hydraulic machinery. The growing emphasis on sustainability and operational efficiency is expected to drive the adoption of these advanced machines across various industries.
Customization and Miniaturization of Molding Machines
The trend of customization and miniaturization in the injection molding machine market is gaining traction. With the demand for increasingly complex and intricate parts, manufacturers are seeking injection molding machines that can produce small, high-precision components for industries such as medical devices, electronics, and automotive. As product designs become more intricate and tailored to specific consumer needs, there is a rising demand for machines capable of handling smaller molds and tighter tolerances. Miniaturized molding machines allow manufacturers to produce components with greater precision and finer detail, meeting the rising requirements for advanced products. This trend is pushing the market toward the development of more compact and adaptable molding machines capable of handling sophisticated production processes.
Integration of Advanced Materials in Molding Machines
Another key trend is the integration of advanced materials into the injection molding process. Manufacturers are increasingly using high-performance polymers, such as engineering plastics, thermoplastic elastomers, and carbon fiber composites, to meet the growing demands of industries like aerospace, automotive, and electronics. Injection molding machines are evolving to handle these new materials, which require specific molding conditions and processing parameters. The adoption of such advanced materials is driven by the need for lightweight, durable, and high-performance components. As industries prioritize material innovation for enhanced functionality and strength, injection molding machine manufacturers are increasingly designing machines that can efficiently process these advanced materials, further expanding the market's capabilities.
Shift Toward Automation and Smart Factories
The shift towards automation and the creation of smart factories is another significant trend in the injection molding machine market. As manufacturing processes become more automated, there is a growing demand for injection molding machines that integrate seamlessly with other automated systems, such as robotic arms, automated storage, and material handling units. The adoption of smart factory technologies, which rely on sensors, IoT devices, and data analytics, is transforming the injection molding process. These technologies enable manufacturers to monitor machine performance in real time, predict maintenance needs, and optimize production schedules for better efficiency. For instance, LS Mtron Ltd., a South Korea-based manufacturer, launched an AI-based smart injection molding system in April 2022, featuring AI Molding Assistant and Smart Weight Control. The former reduces setup time, stabilizing the initial molding process, while the latter detects weight changes in products. As more manufacturers seek to streamline operations and reduce human intervention, the integration of automation and smart technologies into injection molding machines is expected to continue to grow.
Market Challenges Analysis:
High Initial Investment Costs
One of the key restraints in the injection molding machine market is the high initial investment required for purchasing advanced molding machines. While these machines offer long-term benefits in terms of efficiency, precision, and operational cost savings, the upfront cost can be prohibitive for small and medium-sized manufacturers. Additionally, the installation of complex machinery and the need for specialized infrastructure further increase the initial capital expenditure. This significant financial barrier can deter smaller players in the market from adopting new technologies and expanding their production capabilities. Consequently, the high cost of advanced injection molding machines may limit their widespread adoption in certain regions and industries.
Maintenance and Operational Complexity
Another challenge faced by the injection molding machine market is the complexity of machine maintenance and operation. Although modern injection molding machines are equipped with advanced automation and precision features, their maintenance requires skilled personnel and specialized knowledge. The need for regular maintenance, including monitoring and replacing key components like hydraulic systems, motors, and sensors, can lead to increased downtime and operational inefficiencies if not properly managed. Additionally, the operation of these machines requires a high level of expertise, and any errors in the setup or mold design can lead to defects and quality issues in the final product. This complexity can increase operational costs and reduce overall productivity for manufacturers.
Environmental Regulations and Compliance
The injection molding machine market is also challenged by increasing environmental regulations, particularly related to plastic waste management and energy consumption. Governments and regulatory bodies are implementing stricter rules regarding the use of non-recyclable materials and the environmental impact of plastic production. Manufacturers must invest in technologies that ensure compliance with these regulations, which can lead to additional costs and operational adjustments. For instance, companies must comply with various environmental regulations, such as those related to the disposal of hazardous waste and the use of chemicals that are harmful to the environment. The growing pressure to adopt more sustainable practices may limit the flexibility of some injection molding operations, especially in industries that rely heavily on conventional plastic materials.
Market Opportunities:
The injection molding machine market presents significant opportunities in emerging industries, particularly in the fields of medical devices, electronics, and sustainable packaging. As these industries demand increasingly complex and high-performance components, injection molding offers the precision and flexibility required to meet these needs. The growing trend toward miniaturization, coupled with advancements in material science, provides manufacturers with opportunities to develop specialized machines that can handle intricate designs and advanced polymers. For example, in the medical industry, the need for sterile, lightweight, and durable components is driving the demand for injection-molded parts. Similarly, the rise of electric vehicles and consumer electronics presents opportunities for injection molding machines to produce high-quality, lightweight parts that meet strict regulatory and performance standards.
Another key market opportunity lies in the growing focus on sustainability and recycling initiatives. As environmental concerns continue to shape global manufacturing trends, there is an increasing demand for eco-friendly materials and processes. Injection molding machines capable of processing recyclable and biodegradable plastics are gaining traction across industries, especially in packaging and automotive sectors. Manufacturers who adopt sustainable practices and invest in machines that reduce energy consumption and material waste can tap into this growing market segment. Furthermore, the integration of advanced technologies, such as closed-loop systems for recycling plastic waste, offers a unique opportunity to innovate and enhance the market appeal of injection molding machines that align with global sustainability goals.
Market Segmentation Analysis:
The injection molding machine market is segmented across various categories, each contributing to its growth in distinct ways.
By Material Segments
The market is primarily driven by the demand for plastic injection molding machines, which dominate the sector due to their versatility and cost-effectiveness. Rubber, metal, and ceramic materials also represent growing segments, particularly in industries like automotive and healthcare, where specialized parts are required. The "Others" segment includes emerging materials that cater to niche applications, providing innovative solutions to manufacturers.
By Clamping Force Segments
Clamping force plays a crucial role in determining the capacity and precision of injection molding machines. Machines with less than 200 tons of force are commonly used for smaller, high-volume parts. The 200 to 500 tons force segment serves mid-sized production runs, particularly in automotive and consumer goods. Machines with more than 500 tons of force cater to heavy-duty, large-scale applications in industries such as automotive and packaging, requiring robust performance.
By End-Use Segments
The automotive industry remains the largest end-user, as injection molding technology is crucial for producing precision components. The consumer goods segment is also significant, driven by the demand for plastic packaging and everyday products. Packaging and electronics are rapidly expanding segments, with injection molding offering solutions for efficient, high-quality production. The "Others" segment includes medical devices, construction, and other industries utilizing customized molded parts.
By Technology Segments
Hydraulic injection molding machines dominate the market, offering reliable and efficient solutions for a wide range of applications. Electric and hybrid molding machines are gaining popularity due to their energy efficiency, precision, and lower environmental impact, catering to industries focusing on sustainability and advanced manufacturing technologies.
Segmentation:
By Material Segments
- Plastic
- Rubber
- Metal
- Ceramic
- Others
By Clamping Force Segments
- Less Than 200 Tons Force
- 200 To 500 Tons Force
- More Than 500 Tons Force
By End-Use Segments
- Automotive
- Consumer Goods
- Packaging
- Electronics
- Others
By Technology Segments
- Hydraulic
- Electric
- Hybrid
Regional Analysis:
The global injection molding machine market is geographically segmented into five major regions: North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Each region has distinct growth drivers and opportunities, contributing to the overall dynamics of the market.
Asia Pacific: Dominating the Market
Asia Pacific holds the largest share of the global injection molding machine market, accounting for more than 40% of the market share in 2023. This dominance can be attributed to the rapid industrialization and manufacturing growth in countries like China, India, and Japan. The region's robust automotive and electronics sectors, along with a growing demand for consumer goods, significantly contribute to the high adoption of injection molding technology. Furthermore, the presence of leading injection molding machine manufacturers and low labor costs in these countries make it an attractive region for both local and international investments. The growing focus on sustainable manufacturing processes and advancements in automation further support market growth in Asia Pacific.
North America: Steady Growth with Advanced Manufacturing
North America holds a substantial share of the injection molding machine market, accounting for approximately 25% of the market in 2023. The United States is a major contributor to the region's market size, driven by strong automotive, consumer electronics, and medical device manufacturing industries. The region's adoption of advanced technologies, such as electric and hybrid molding machines, is further propelling growth. Additionally, the increasing focus on sustainable production practices and compliance with environmental regulations creates opportunities for manufacturers to innovate and adopt more energy-efficient machines. While the market growth rate in North America is steady, the demand for high-quality, precision-engineered parts continues to fuel investments in injection molding technology.
Europe: Strong Automotive and Healthcare Sectors
Europe holds a significant portion of the global market, with a share of around 20%. Countries like Germany, France, and Italy are key players, particularly due to their advanced automotive and healthcare industries. The demand for lightweight and durable components, along with innovations in material science, drives the growth of injection molding machines in the region. Germany, known for its automotive manufacturing excellence, plays a crucial role in this market segment. Additionally, the shift towards sustainable packaging and eco-friendly materials in various sectors, including packaging and consumer goods, creates further demand for advanced injection molding machines that can process recyclable and biodegradable materials.
Latin America and the Middle East & Africa: Emerging Markets with Growth Potential
Latin America and the Middle East & Africa represent emerging markets in the injection molding machine sector. Latin America holds a smaller market share, estimated at around 7%, but it is expected to experience steady growth due to the expanding automotive and packaging industries in countries like Brazil and Mexico. The Middle East & Africa, with a market share of about 5%, is witnessing gradual industrialization, with increasing demand for injection-molded parts in the automotive, construction, and packaging sectors. As these regions continue to develop their manufacturing capabilities, they offer untapped potential for the adoption of injection molding machines.
Key Player Analysis:
- Arburg GmbH + Co KG
- Haitian International Holdings Limited
- Milacron
- Nissei Plastic Industrial Co., Limited
- Sumitomo (SHI) Demag Plastics Machinery GmbH
- Company 6
- Company 7
- Company 8
- Company 9
- Company 10
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis:
The injection molding machine market is highly competitive, with a mix of established global players and regional manufacturers. Key companies such as Arburg GmbH, Engel Austria GmbH, and Husky Injection Molding Systems dominate the market, offering a wide range of high-performance machines designed for various industries, including automotive, medical, and consumer goods. These industry leaders focus on continuous innovation, enhancing machine precision, energy efficiency, and automation capabilities, catering to the increasing demand for advanced manufacturing solutions. Regional players, such as Milacron and Sumitomo (SHI) Demag, are also significant contributors, offering cost-effective solutions to emerging markets. The growing emphasis on sustainability and energy efficiency has prompted manufacturers to invest in hybrid and electric machines, further intensifying competition. Companies are increasingly focusing on strategic partnerships, mergers, and acquisitions to expand their product portfolios and regional presence, aiming to meet the evolving demands of diverse industries.
Recent Developments:
- In April 2022, LS Mtron Ltd., a South Korean manufacturer, launched an advanced artificial intelligence (AI)-based smart injection molding system. This innovative system features two key technological components: 'AI Molding Assistant' and 'Smart Weight Control'. The AI Molding Assistant is designed to reduce setup time and stabilize the initial molding process, while the Smart Weight Control is integrated into the injection molding machine's software to detect product weight changes, enhancing overall production efficiency.
- In December 2022, SOLIZE India Technologies, a subsidiary of SOLIZE Corporation, formed a partnership with Toray Engineering D Solutions. This collaboration aims to supply 3D injection molding machines to the Indian market, potentially revolutionizing the manufacturing landscape in the country.
- In March 2025, Bain Capital Special Situations announced a majority investment in the Milacron injection molding and extrusion business. The investment firm will partner with Milacron's current owner, Hillenbrand Inc., which will remain a significant investor, to accelerate the company's continued growth.
Market Concentration & Characteristics:
The injection molding machine market exhibits moderate to high concentration, with a few large players holding significant market shares, particularly in developed regions. Companies such as Arburg GmbH, Engel Austria GmbH, Husky Injection Molding Systems, and Milacron dominate the global landscape, commanding a substantial portion of the market through their extensive product portfolios and strong brand presence. These leaders focus on technological advancements, including electric and hybrid molding machines, automation, and sustainability features, to maintain competitive advantages. However, the market also features numerous regional players catering to specific local demands, particularly in emerging economies. These companies offer cost-effective, customized solutions, contributing to the fragmented nature of the market in these regions. The market is characterized by constant innovation, with companies investing heavily in R&D to meet the evolving needs for precision, energy efficiency, and the ability to process advanced materials
Report Coverage:
The research report offers an in-depth analysis based on By Material Segments, By Clamping Force Segments, By End-Use Segments and By Technology Segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The injection molding machine market is expected to experience sustained growth over the coming years.
- Rising demand for lightweight, durable materials across industries such as automotive and aerospace will propel market expansion.
- Advancements in automation and AI will significantly enhance machine precision and operational efficiency.
- Hybrid and electric molding machines will become increasingly popular due to their energy efficiency and reduced environmental impact.
- The growing need for miniaturized, high-precision parts in medical devices and electronics will drive further market growth.
- Rapid industrialization in emerging economies will lead to widespread adoption of injection molding technology.
- A focus on sustainability will lead to a rise in the use of eco-friendly materials and recycling capabilities in molding processes.
- The integration of smart factory technologies and IoT-enabled molding machines will boost production efficiency.
- Regional players will offer cost-effective solutions, increasing competition in the global injection molding market.
- Ongoing innovations in material science and mold design will open new opportunities for high-performance applications in various industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Injection Molding Machine Market?
What factors are driving the growth of the Injection Molding Machine Market?
What are the key segments within the Injection Molding Machine Market?
What are some challenges faced by the Injection Molding Machine Market?
Who are the major players in the Injection Molding Machine Market?
Which segment is leading the Injection Molding Machine Market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Injection Molding Machine Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Injection Molding Machine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 709.8 million → 2032: USD 1343.27 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Injection Molding Machine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Injection Molding Machine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Injection Molding Machine Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Injection Molding Machine Market Drivers
- 3.3 Injection Molding Machine Market Restraints & Challenges
- 3.4 Injection Molding Machine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Injection Molding Machine Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Injection Molding Machine Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Injection Molding Machine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Injection Molding Machine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Injection Molding Machine Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Injection Molding Machine market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Injection Molding Machine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Injection Molding Machine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Injection Molding Machine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Injection Molding Machine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Injection Molding Machine Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Injection Molding Machine Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Injection Molding Machine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Injection Molding Machine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Injection Molding Machine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Injection Molding Machine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Injection Molding Machine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Injection Molding Machine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Injection Molding Machine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
