
Market Overview:
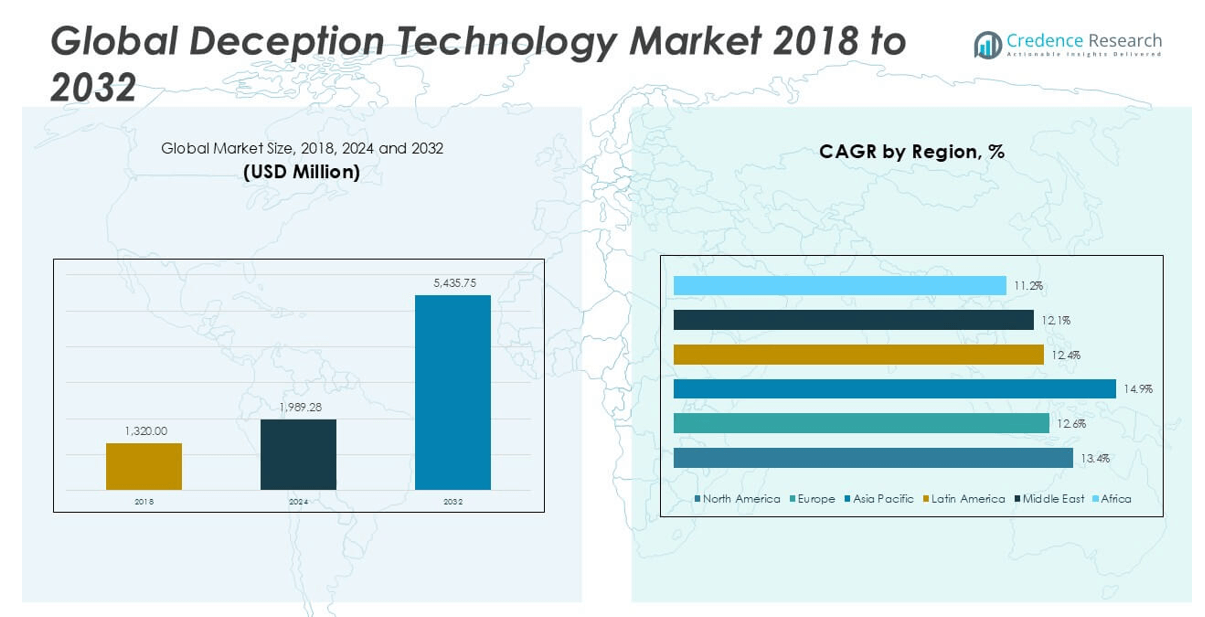
The Deception Technology market size was valued at USD 1,320.00 million in 2018, increased to USD 1,989.28 million in 2024, and is anticipated to reach USD 5,435.75 million by 2032, at a CAGR of 13.44% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Deception Technology Market Size 2024 | USD 1,989.28 million |
| Deception Technology Market , CAGR | 13.44% |
| Deception Technology Market Size 2032 | USD 5,435.75 million |
The Deception Technology market is highly competitive, led by key players such as Acalvio Technologies, Attivo Networks, Illusive Networks, Rapid7, and LogRhythm, Inc. These companies dominate through advanced product offerings, strategic partnerships, and strong R&D investments focused on AI-driven and cloud-compatible deception solutions. Emerging firms like Smokescreen Technologies and Cymmetria are also gaining market presence, particularly among SMEs seeking agile cybersecurity tools. Regionally, North America holds the largest share of the global market at 36.4% in 2024, driven by strong cybersecurity infrastructure, early adoption of advanced technologies, and high investment across industries such as finance, healthcare, and government.
Market Insights
- The Deception Technology market was valued at USD 1,989.28 million in 2024 and is projected to reach USD 5,435.75 million by 2032, growing at a CAGR of 13.44% during the forecast period.
- Rising cyber threats, including advanced persistent threats and insider attacks, are driving demand for deception-based security tools that offer real-time detection and low false positives.
- The market is witnessing a trend toward AI-integrated and cloud-based deception platforms, with network security being the dominant sub-segment due to increasing lateral movement attacks.
- The market is moderately fragmented, with key players like Acalvio Technologies, Attivo Networks, Rapid7, and Illusive Networks investing in innovation, but adoption is restrained by limited awareness and integration challenges with legacy systems.
- North America leads the regional market with a 36.4% share, followed by Europe at 25.5% and Asia Pacific at 24.5%; the solution segment dominates by component, accounting for over 60% of the market share in 2024.
Market Segmentation Analysis:
By Component
In the Deception Technology market, the solution segment holds the dominant market share, accounting for over 60% in 2024. This segment’s growth is driven by the increasing demand for advanced threat detection and response capabilities across enterprises. Deception solutions offer high-fidelity alerts and real-time threat intelligence, which significantly reduce false positives and enhance the efficiency of security operations. As cyberattacks grow in sophistication, organizations are prioritizing robust and proactive security frameworks, further propelling the adoption of deception-based software solutions across various industry verticals.
- For instance, Attivo Networks' ThreatDefend platform was deployed across over 7,000 endpoints in a U.S.-based financial institution, enabling a 90% reduction in dwell time for threats through decoy-based detection mechanisms.
By Deception Stack
Among the deception stack segments, network security emerged as the leading sub-segment, capturing the highest market share in 2024. This dominance is attributed to the rising complexity of network infrastructures and the growing incidence of lateral movement attacks. Deception-based network security tools such as decoy servers, routers, and switches help in misleading attackers and identifying intrusions before damage is done. The increased investment in network architecture modernization and the rising awareness of advanced persistent threats (APTs) are fueling the demand for deception technology in this stack.
- For instance, Illusive Networks reported successful deployment of over 500 deceptive network nodes at a global pharmaceutical company, which led to the early detection of a simulated lateral attack within 3 minutes of initial breach.
By Deployment
The cloud deployment model has gained significant traction and now holds a dominant share in the Deception Technology market, accounting for more than half of the global revenue in 2024. The shift toward cloud environments across enterprises, driven by scalability, flexibility, and cost-efficiency, has spurred demand for cloud-based deception platforms. These solutions enable remote threat monitoring and seamless integration with existing cloud-native architectures. The rising frequency of cloud-based attacks and the need for dynamic threat detection across hybrid and multi-cloud infrastructures are key drivers contributing to the growth of this deployment model.
Market Overview
Rising Sophistication of Cyber Threats
The increasing complexity and frequency of cyberattacks, such as ransomware, advanced persistent threats (APTs), and insider threats, are significantly driving the demand for deception technology. Traditional security tools often fail to detect such stealthy threats in real time. Deception technology offers proactive defense mechanisms by creating traps and decoys that lure attackers, enabling faster threat detection and response. As organizations face mounting pressure to safeguard critical data, especially in sectors like BFSI, government, and healthcare, the adoption of deception tools continues to accelerate globally.
- For instance, Rapid7 integrated deception into its InsightIDR platform, detecting over 2,300 early-stage insider threat activities across 200 monitored organizations in 2023.
Growing Need for High-Fidelity Threat Detection
One of the major advantages of deception technology is its ability to deliver high-fidelity alerts with minimal false positives. Unlike conventional security tools that flood security teams with excessive alerts, deception-based systems only trigger alarms when decoys are accessed-indicating real malicious activity. This capability enhances operational efficiency and strengthens incident response times. As enterprises seek more precise and actionable threat intelligence, the demand for technologies that reduce alert fatigue and improve security analytics is becoming a critical driver for market growth.
- For instance, LogRhythm’s integration with Smokescreen’s deception technology in 2023 resulted in a 73% decrease in false positive alerts in a six-month deployment at a regional energy provider.
Expansion of Cloud and IoT Ecosystems
The rapid proliferation of cloud-based infrastructure and the Internet of Things (IoT) has expanded the digital attack surface, making traditional perimeter defenses less effective. Deception technology, with its scalable and adaptive approach, is well-suited for protecting cloud-native applications and interconnected IoT devices. Its ability to integrate seamlessly across hybrid and multi-cloud environments enhances visibility and control. As organizations migrate more operations to the cloud and deploy smart devices, the need for deception-based solutions to monitor and secure these dynamic environments is expected to grow significantly.
Key Trends & Opportunities
Integration with AI and Automation
The integration of artificial intelligence (AI) and machine learning (ML) with deception technology is emerging as a transformative trend. AI-powered deception platforms can automatically adapt to attacker behavior, enhancing the realism of decoys and improving threat detection accuracy. Automation also streamlines incident response by correlating data and triggering countermeasures without human intervention. These innovations enable faster threat containment and reduce operational overhead, presenting a lucrative opportunity for vendors to offer smarter, self-learning deception systems to meet evolving cybersecurity needs.
- For instance, Acalvio’s ShadowPlex AI engine processed over 1.2 million threat signals per month and autonomously generated adaptive decoys for over 200 enterprise environments in 2024.
Rising Demand Across SMEs and Emerging Markets
Small and medium-sized enterprises (SMEs) and organizations in emerging economies are increasingly adopting deception technology as it becomes more affordable and easier to deploy. The growing awareness of cybersecurity risks and the need to comply with data protection regulations are encouraging smaller firms to invest in proactive security measures. Vendors are capitalizing on this opportunity by offering cloud-based, scalable solutions tailored to SMEs. Additionally, government-led digital transformation initiatives in regions such as Asia Pacific and Latin America are expanding the market's geographic reach.
- For instance, Cymmetria deployed its MazeRunner deception platform in over 85 SMEs across Southeast Asia in 2023, enabling early detection of more than 1,100 phishing-based lateral movements within the first 30 days of use.
Key Challenges
Limited Awareness and Skill Gap
Despite its benefits, deception technology still faces limited awareness among potential users, especially in small enterprises and traditional industries. Many decision-makers are unfamiliar with how deception works or doubt its effectiveness compared to conventional tools. Moreover, the shortage of skilled cybersecurity professionals who can deploy and manage deception systems adds to the challenge. This knowledge and talent gap restricts market penetration, underscoring the need for increased education, training, and vendor support to bridge the adoption barrier.
Integration Complexity with Legacy Systems
Integrating deception technology into existing legacy IT infrastructures can be complex and resource-intensive. Many organizations operate with outdated systems that lack the flexibility to accommodate advanced security tools without major overhauls. Customization, compatibility issues, and network performance concerns may hinder seamless deployment. These challenges lead to longer implementation cycles and increased costs, especially for organizations with limited budgets or stretched IT resources. As a result, some businesses hesitate to adopt deception solutions despite recognizing their value.
Regulatory and Privacy Concerns
Deception technology operates by simulating environments and tracking attacker behavior, which may raise concerns about compliance with data protection and privacy regulations such as GDPR or CCPA. Misuse or misconfiguration of decoys could inadvertently capture personal data or affect user privacy. Organizations must navigate legal considerations carefully when deploying deception tools to avoid regulatory penalties. Vendors must also ensure their solutions comply with global data governance standards, which can complicate product development and limit market scalability in highly regulated regions.
Regional Analysis
North America
North America dominated the Deception Technology market in 2024 with a market share of approximately 36.4%, valued at USD 724.68 million, up from USD 486.68 million in 2018. The market is projected to reach USD 1,977.53 million by 2032, registering a CAGR of 13.4% during the forecast period. The region's dominance is attributed to strong cybersecurity infrastructure, early technology adoption, and growing threats from sophisticated cyberattacks. Regulatory mandates and significant investments by government and private organizations further support market growth. The U.S. holds a leading position due to its advanced digital landscape and concentration of major market players.
Europe
Europe held a 25.5% share of the global Deception Technology market in 2024, with revenues reaching USD 506.81 million, up from USD 349.80 million in 2018. The market is forecast to expand to USD 1,308.67 million by 2032, registering a CAGR of 12.6%. The regional growth is driven by increasing regulatory requirements like GDPR, combined with a rising focus on data privacy and network protection. Countries such as Germany, the UK, and France are leading adopters, driven by growing demand from the BFSI and healthcare sectors. Cybersecurity investments continue to grow amid increasing incidents of ransomware and insider threats.
Asia Pacific
Asia Pacific accounted for 24.5% of the global Deception Technology market in 2024, reaching USD 487.07 million, up from USD 308.88 million in 2018. The market is expected to grow to USD 1,474.72 million by 2032, exhibiting the highest CAGR of 14.9% among all regions. Rapid digitalization, growing reliance on cloud infrastructure, and increasing cyber threats are fueling demand across emerging economies like China, India, and Southeast Asia. Government-led cybersecurity initiatives and the expansion of smart city and industrial IoT projects also contribute to regional growth. The region’s large consumer base and digital infrastructure upgrades offer strong opportunities.
Latin America
Latin America held a 6.5% share of the Deception Technology market in 2024, with a market size of USD 129.68 million, growing from USD 86.86 million in 2018. It is projected to reach USD 329.79 million by 2032, expanding at a CAGR of 12.4%. Market growth is fueled by the increasing need for robust cybersecurity frameworks amid rising threats targeting financial institutions and critical infrastructure. Countries like Brazil and Mexico are emerging as key markets, with rising investments in IT modernization and cloud technologies. Additionally, improved regulatory focus on data protection is promoting wider adoption of deception solutions.
Middle East
The Middle East captured a 3.9% share of the global Deception Technology market in 2024, with a value of USD 77.17 million, up from USD 54.38 million in 2018. The market is forecast to grow to USD 191.91 million by 2032, at a CAGR of 12.1%. The region is witnessing increased adoption of cybersecurity tools amid growing geopolitical threats and digital transformation initiatives. Sectors like oil & gas, government, and finance are key drivers of demand. Gulf Cooperation Council (GCC) countries, particularly the UAE and Saudi Arabia, are investing heavily in cybersecurity resilience and digital infrastructure, supporting market expansion.
Africa
Africa accounted for 3.2% of the global Deception Technology market in 2024, valued at USD 63.86 million, a significant rise from USD 33.40 million in 2018. The market is expected to reach USD 153.12 million by 2032, growing at a CAGR of 11.2%. Despite a relatively smaller market size, the region is witnessing rising awareness about cyber risks and digital security needs. Growth is driven by increased mobile and internet penetration, government digital programs, and the need to protect financial services and public sector data. South Africa, Nigeria, and Kenya are among the leading adopters of deception-based cybersecurity technologies.
Market Segmentations:
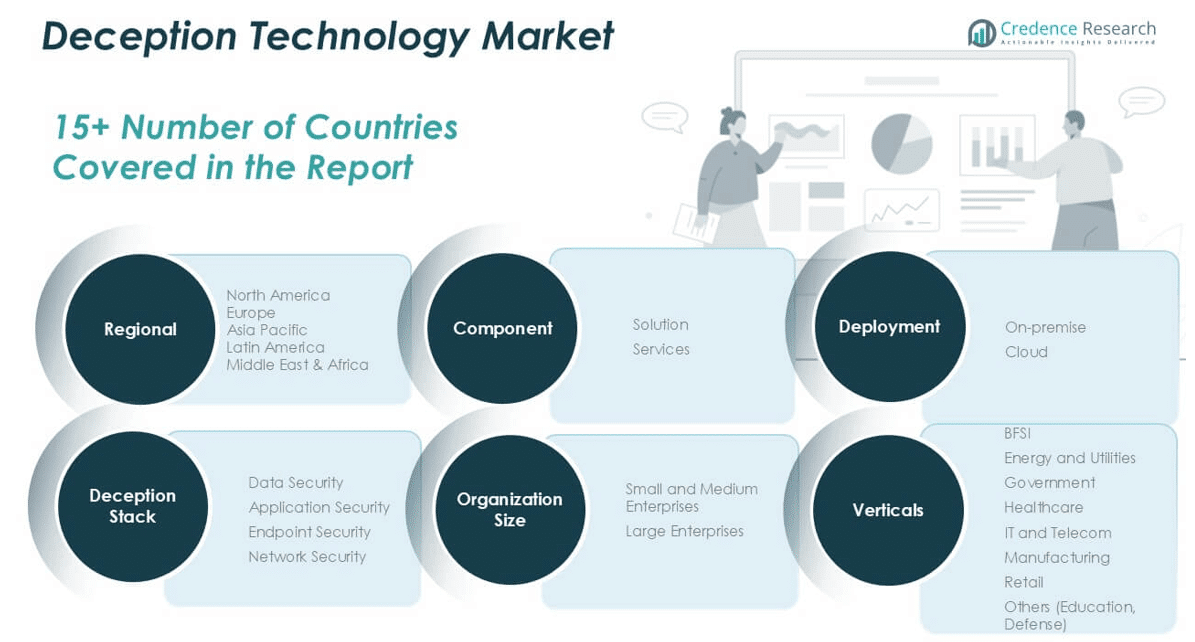
By Component
- Solution
- Services
By Deception Stack
- Data Security
- Application Security
- Endpoint Security
- Network Security
By Deployment
- On-premise
- Cloud
By Organization Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
By Verticals
- BFSI
- Energy and Utilities
- Government
- Healthcare
- IT and Telecom
- Manufacturing
- Retail
- Others (Education, Defense)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Deception Technology market is characterized by the presence of several innovative players focused on developing advanced threat detection and response solutions. Key companies such as Acalvio Technologies, Attivo Networks, Illusive Networks, Rapid7, and LogRhythm are leading the market through continuous innovation, strategic partnerships, and product enhancements. These players are investing heavily in AI-driven deception platforms, cloud compatibility, and automation to meet the evolving needs of enterprises across sectors such as BFSI, healthcare, and government. Startups like Smokescreen Technologies and Cymmetria are gaining traction by offering lightweight, cost-effective solutions tailored for SMEs. Mergers, acquisitions, and collaborations remain key strategic moves to expand geographical presence and product portfolios. Additionally, vendors are focusing on strengthening their threat intelligence capabilities and improving integration with SIEM and SOAR platforms to deliver end-to-end security solutions. As cyber threats grow more sophisticated, competition is intensifying, driving innovation and market consolidation in this rapidly evolving landscape.
Key Player Analysis
- Acalvio Technologies
- Allure Security Technology, Inc.
- Attivo Networks, Inc.
- Cymmetria, Inc.
- Guardicore Ltd
- Illusive Networks
- LogRhythm, Inc.
- Rapid7, Inc.
- Smokescreen Technologies
- Topspin Security
- TrapX Security
- vArmour
Recent Developments
- In July 2025, Acalvio Technologies maintained its leadership in deception technology, notably recognized in the 2025 GigaOm Radar report for its ShadowPlex Cyber Deception Platform. The report highlighted Acalvio's strengths in cost, scalability, and flexibility. Acalvio's Fluid Deception technology, powered by AI, enhances deception deployment and event triage, with new features focused on cloud environments and automated threat response.
- In February 2023, Acalvio Technologies introduced its Identity Threat Detection and Response (ITDR) solution, a cybersecurity tool that utilizes deception techniques to proactively identify and detect credential-based attacks by strategically placing "decoy" accounts and credentials (known as honeytokens) within a network to trap attackers and gain valuable threat intelligence.
- In May 2022, SentinelOne acquired Attivo Networks, enhancing its cybersecurity platform with Attivo's deception technology and identity assessment capabilities. This integration aimed to strengthen SentinelOne's real-time infrastructure defense and identity threat detection and response. The acquisition focused on fortifying identity and environment defense, particularly in the context of zero-trust adoption.
- In September 2024, Rapid7 acquired a deception technology startup to enhance its InsightIDR platform. This acquisition bolsters Rapid7's threat detection and response capabilities by integrating deception technology, which aims to detect lateral movement, insider threats, and advanced attacks using AI-driven techniques.
Market Concentration & Characteristics
The Deception Technology Market exhibits moderate to high market concentration, with a mix of established cybersecurity firms and emerging specialists competing to deliver advanced threat detection solutions. Key players such as Attivo Networks, Acalvio Technologies, Illusive Networks, and Rapid7 dominate through robust product portfolios, strategic alliances, and continuous innovation. It features a strong emphasis on real-time threat intelligence, low false-positive alerts, and proactive security measures. The market is defined by rapid technological advancements, with vendors focusing on AI, automation, and cloud-native integrations. It caters to a wide range of industries including BFSI, healthcare, and government, reflecting strong cross-sector demand. Cloud deployment and network security remain dominant sub-segments, supported by rising demand for scalable and adaptive security frameworks. Buyers prioritize integration ease and operational efficiency, driving solution providers to offer modular, interoperable platforms. The market also reflects a growing interest from small and medium enterprises due to the availability of cost-effective, lightweight deception tools. While North America holds the largest share, Asia Pacific shows the fastest growth driven by digital transformation and cybersecurity initiatives.
Report Coverage
The research report offers an in-depth analysis based on Component, Deception Stack, Deployment, Organization Size, Verticals and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The deception technology market will continue to grow rapidly due to increasing cyber threats and the demand for proactive security solutions.
- Organizations across sectors will increasingly adopt deception tools to detect advanced persistent threats and insider attacks.
- Integration of artificial intelligence and machine learning will enhance the accuracy and adaptability of deception platforms.
- Cloud-based deception solutions will gain more traction as enterprises shift to hybrid and multi-cloud environments.
- Small and medium enterprises will emerge as key adopters due to the availability of scalable and affordable deception tools.
- Regulatory pressure for data protection and breach detection will drive adoption in highly regulated industries.
- Vendors will focus on improving interoperability with existing SIEM and SOAR platforms to streamline threat response.
- Emerging markets in Asia Pacific and Latin America will present significant growth opportunities due to digital transformation initiatives.
- Continued innovation in decoy diversity and deployment automation will improve solution efficiency and adoption rates.
- Strategic partnerships, acquisitions, and product diversification will remain key strategies for market expansion and competitive advantage.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Sophistication of Cyber Threats
The increasing complexity and frequency of cyberattacks, such as ransomware, advanced persistent threats (APTs), and insider threats, are driving organizations to adopt deception technology for proactive defense and faster threat detection.
Demand for High-Fidelity Threat Detection
Deception technology delivers high-fidelity alerts with minimal false positives, enabling security teams to focus on genuine threats and improving operational efficiency, which is a key factor for enterprises overwhelmed by alert fatigue.
Expansion of Cloud and IoT Ecosystems
The proliferation of cloud infrastructure and IoT devices has expanded the attack surface, making deception technology essential for monitoring and securing dynamic, hybrid, and multi-cloud environments.
Integration with AI and Automation
The adoption of AI and machine learning in deception platforms enhances the realism of decoys, automates threat response, and improves detection accuracy, making these solutions more attractive to organizations seeking advanced, adaptive security.
Regulatory Pressure and Data Protection Requirements
Stricter data protection regulations and compliance mandates in sectors like BFSI, healthcare, and government are compelling organizations to implement deception technology for improved breach detection and regulatory adherence.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Deception Technology Market?
What are the main drivers behind the growth of the Deception Technology Market?
How does deception technology work?
Why are businesses adopting deception technology?
Which regions are leading the Deception Technology Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Solution
- 1.2.2 Services
- 1.3 By Verticals
- 1.3.1 BFSI
- 1.3.2 Healthcare
- 1.3.3 Government
- 1.3.4 IT and Telecom
- 1.3.5 Manufacturing
- 1.3.6 Retail
- 1.3.7 Energy and Utilities
- 1.3.8 Others (Education, Defense)
- 1.4 By Deployment
- 1.4.1 On-premise
- 1.4.2 Cloud
- 1.5 By Deception Stack
- 1.5.1 Data Security
- 1.5.2 Application Security
- 1.5.3 Endpoint Security
- 1.5.4 Network Security
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,989.28 million → 2032: USD 5,435.75 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Deception Technology Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Deception Technology Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Deception Technology Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Deception Technology Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Deception Technology Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Deception Technology Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Deception Technology Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Deception Technology Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,989.28 million → 2032: USD 5,435.75 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Deception Technology Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Solution
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Verticals - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 BFSI
- 12.4.7.2 Healthcare
- 12.4.7.3 Government
- 12.4.7.4 IT and Telecom
- 12.4.7.5 Manufacturing
- 12.4.7.6 Retail
- 12.4.7.7 Energy and Utilities
- 12.4.7.8 Others (Education, Defense)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-premise
- 12.5.7.2 Cloud
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Deception Stack - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Data Security
- 12.6.7.2 Application Security
- 12.6.7.3 Endpoint Security
- 12.6.7.4 Network Security
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Deception Technology End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Deception Technology Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Deception Technology Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Deception Technology Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Acalvio Technologies
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Attivo Networks
- 18.4 Illusive Networks
- 18.5 Rapid7
- 18.6 LogRhythm, Inc.
- 18.7 Smokescreen Technologies
- 18.8 Cymmetria
- 18.9 TrapX Security
- 18.10 Allure Security Technology, Inc.
- 18.11 SentinelOne
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

