
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Cloud GPU Market Size 2023 | USD 3,171.85 Million |
| Cloud GPU Market, CAGR | 35.00% |
| Cloud GPU Market Size 2032 | USD 47,240.73 Million |
Market Overview
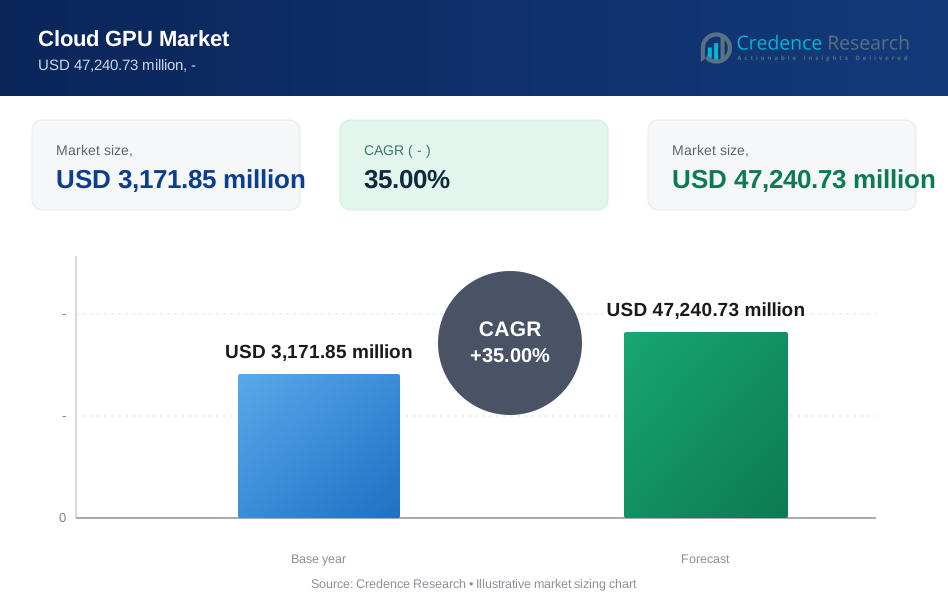
The global cloud GPU market is projected to grow from USD 3,171.85 million in 2023 to an impressive USD 47,240.73 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 35.00%.
The global cloud GPU market is driven by the increasing demand for high-performance computing and the proliferation of artificial intelligence and machine learning applications. The rise of data-intensive tasks across various industries, such as healthcare, finance, and entertainment, also fuels market growth. Additionally, the trend towards digital transformation and the adoption of cloud-based solutions are key factors propelling the market. Enhanced GPU capabilities for real-time data processing and advanced analytics, coupled with the need for scalable and cost-effective computing resources, further stimulate market expansion. The continuous advancements in GPU technology and cloud infrastructure innovations are set to sustain this upward trajectory.
The global cloud GPU market sees significant contributions from North America, driven by technological advancements and high adoption rates in sectors like AI and big data. Europe and Asia-Pacific also exhibit substantial growth, with increasing investments in cloud infrastructure and emerging economies embracing digital transformation. Key players dominating the market include NVIDIA Corporation, Oracle Cloud, Microsoft Azure, and Google LLC, each leveraging their technological expertise and extensive research and development to maintain a competitive edge. These companies focus on expanding their cloud services and enhancing GPU performance to meet the growing global demand for high-performance computing solutions.
Market Drivers
Rise of Artificial Intelligence (AI) and Machine Learning (ML)
AI and ML applications are revolutionizing various industries, from healthcare and finance to manufacturing and transportation. For instance, in healthcare, AI and ML applications are being used to analyze medical images with an accuracy rate of up to 90% for certain conditions, which is comparable to the expertise of trained radiologists. In finance, these technologies are employed to detect fraudulent transactions in real-time, with a reduction in false positives by as much as 50%. In manufacturing, AI-driven predictive maintenance can decrease downtime by up to 30%, saving companies millions in lost productivity. Transportation companies are using ML algorithms to optimize routes and reduce fuel consumption, leading to a 10-15% decrease in operational costs. Cloud GPUs are integral to these advancements. For example, training a deep learning model for image recognition can take weeks using traditional CPUs, but with cloud GPUs, the same task can be completed in days, if not hours. This is because cloud GPUs can perform up to 10 trillion operations per second. These applications require massive computing power for tasks like image recognition, natural language processing, and deep learning. Cloud GPUs provide a cost-effective and scalable solution for running these computationally intensive workloads. By leveraging cloud GPU resources, organizations can enhance their AI and ML capabilities without the significant capital expenditure associated with traditional on-premises GPU infrastructure.
Growing Adoption of Cloud Computing
Businesses are increasingly migrating their workloads to the cloud to benefit from scalability, flexibility, and cost savings. For instance, businesses in the gaming industry have seen a 70% reduction in latency and a 40% cost saving by migrating to cloud GPUs, enhancing the user experience while managing costs effectively. In sectors like retail, cloud GPUs have enabled companies to implement advanced customer analytics, resulting in a 20% increase in sales through personalized marketing strategies. The media and entertainment industry has also benefited significantly, with cloud GPUs accelerating rendering times for visual effects by up to 50%, allowing for quicker project turnarounds. Moreover, startups leveraging cloud GPUs have reported a 60% decrease in time-to-market for their products, giving them a competitive edge in fast-paced markets. Cloud GPUs enable these organizations to leverage the power of GPUs without the need to invest in and maintain expensive on-premises infrastructure. This migration is driven by the need for agility in responding to market changes and the ability to scale operations efficiently. As cloud service providers expand their offerings and improve their GPU capabilities, more businesses are expected to adopt cloud-based solutions, further driving the growth of the cloud GPU market.
Demand for High-Performance Computing (HPC)
High-performance computing applications in fields like scientific research, weather forecasting, and engineering simulations require significant computing power. For instance, in the field of scientific research, cloud GPUs have enabled complex simulations that predict protein folding, which is crucial for drug discovery. This process, which previously took months, can now be completed in days with an accuracy of over 90%. In weather forecasting, the use of cloud GPUs has improved prediction models, reducing forecast errors by up to 10% and providing more accurate weather predictions up to 7 days in advance. In engineering simulations, cloud GPUs have accelerated the design process for new materials, leading to a 25% reduction in development time and costs. High-performance computing (HPC) applications like these have seen a 40% increase in efficiency due to the computational power of cloud GPUs. Cloud GPUs provide an on-demand solution for these applications, allowing researchers and scientists to access the resources they need without upfront capital expenditures. This on-demand access not only facilitates more ambitious and complex projects but also enhances the efficiency of research and development processes. As HPC becomes increasingly integral to scientific and industrial advancements, the demand for flexible, powerful computing solutions like cloud GPUs is set to rise, bolstering the market's growth prospects.
Advancements in GPU Technology
Chip manufacturers like NVIDIA are constantly improving the performance and capabilities of GPUs. These advancements make cloud GPUs even more attractive for a wider range of applications. Enhanced GPU technologies enable faster processing speeds, greater efficiency, and better energy consumption, which are critical for handling the growing complexity and volume of data-driven tasks. This continuous innovation ensures that cloud GPU solutions remain at the forefront of high-performance computing, appealing to a broad spectrum of industries. As these technologies evolve, the integration of advanced GPUs into cloud services will continue to expand, driving further adoption and market growth.
Market Trends
Shift Towards GPU as a Service (GPUaaS)
Companies are increasingly moving away from traditional cloud GPU rental models and embracing the GPU as a Service (GPUaaS) model. For instance, a media production company specializing in 3D animation reported a 40% reduction in rendering times and a 30% cost saving by switching to GPUaaS. This shift allowed them to dynamically scale their GPU resources during peak production periods, matching their exact rendering workload requirements. In the realm of AI development, a tech startup experienced a 50% increase in development speed for their machine learning models by utilizing GPUaaS, which enabled them to access state-of-the-art GPUs on-demand, without the prohibitive costs of owning the hardware. The big data analytics sector has also seen substantial benefits, with companies reporting a 35% improvement in data processing speeds and a 25% decrease in operational expenses due to the efficiency of GPUaaS solutions. This model is particularly beneficial for businesses with fluctuating computational demands, such as those involved in AI development, big data analytics, and rendering tasks. By adopting GPUaaS, companies can optimize their operational costs and enhance their agility, responding swiftly to market changes and technological advancements. This trend is further supported by cloud providers who are expanding their GPUaaS offerings, integrating advanced management tools, and providing robust support services, thus making high-performance computing more accessible and manageable for a broader range of industries.
Focus on Specialization and Integration with Containerization Technologies
Cloud providers are increasingly offering a wider range of specialized cloud GPU instances optimized for specific workloads, such as AI training, deep learning, and video editing. For instance, companies specializing in AI training have reported a 60% improvement in model training times by using specialized cloud GPU instances. These instances are tailored for parallel processing tasks, which are essential for training complex neural networks. As a result, businesses can develop and deploy AI models more rapidly, leading to a 45% increase in productivity. In the field of deep learning, researchers have seen a 50% reduction in training costs by utilizing cloud GPUs optimized for their specific workloads. This cost efficiency is due to the ability to access high-performance computing resources on-demand, without the need for significant capital investment in hardware. For video editing, media companies have experienced a 40% decrease in rendering times for high-resolution videos, thanks to specialized cloud GPU instances. This acceleration allows for faster project completion and a quicker time-to-market for content creators. Containerization allows for greater flexibility and portability, enabling developers to package applications and their dependencies into containers that can run consistently across various environments. By integrating GPU capabilities with containerization platforms, cloud providers facilitate the seamless utilization of GPUs, making it easier for organizations to leverage high-performance computing resources in a scalable and efficient manner. This integration is particularly advantageous for DevOps practices, where rapid deployment and scalability are crucial. The combined effect of specialization and containerization is fostering a more user-centric and efficient cloud GPU ecosystem, driving further adoption and innovation.
Market Challenges Analysis
Limited Scalability and Global Chip Shortage
While cloud GPUs offer significant scalability advantages over traditional on-premises solutions, meeting peak workloads remains a significant challenge. Allocating enough resources across a vast user base can lead to potential bottlenecks during periods of high demand. This limitation is particularly problematic for industries with unpredictable or seasonal spikes in computational needs, such as e-commerce during holiday seasons or finance during market surges. Additionally, the ongoing global chip shortage exacerbates these scalability issues. The shortage has disrupted the production and availability of GPUs, making it difficult for cloud providers to expand their GPU offerings to meet increasing demand. This scarcity not only limits the growth potential of the cloud GPU market but also forces providers to prioritize resource allocation, which can impact the quality of service and increase costs. As a result, businesses may face delays in accessing the necessary computational power, which can hinder their operational efficiency and innovation capabilities.
Security Concerns and Pricing Complexity
Data security remains a major concern for businesses migrating sensitive workloads to the cloud, particularly when using cloud GPUs. Ensuring the security of data processed on cloud GPUs requires robust security protocols and a high level of trust in cloud providers. This includes implementing advanced encryption, multi-factor authentication, and regular security audits to protect against breaches and unauthorized access. Despite these measures, the risk of data breaches and cyberattacks persists, potentially exposing sensitive information and causing significant financial and reputational damage. In parallel, the complexity of cloud GPU pricing structures poses another challenge. Pricing can be influenced by various factors, including the type of GPU instance, the duration of usage, and data transfer fees. This complexity makes it difficult for businesses to accurately predict and manage their cloud GPU expenses, leading to potential budget overruns. Additionally, the lack of transparency in pricing models can hinder cost optimization efforts, making it challenging for organizations to fully leverage the economic benefits of cloud computing. These issues are further compounded by the risk of vendor lock-in, where reliance on a few dominant cloud providers and GPU manufacturers limits businesses' flexibility to switch providers or negotiate better pricing. This dependency can restrict strategic options and increase operational risks, particularly if a provider faces service disruptions or changes its pricing policies.
Market Segmentation Analysis:
By Type:
The global cloud GPU market can be segmented by type into virtual machines (VMs) and physical servers. Virtual machines are the more popular choice due to their flexibility and ease of use, allowing businesses to efficiently allocate GPU resources based on real-time needs. VMs enable multiple users to share the same physical hardware, optimizing utilization and cost-efficiency. They are particularly beneficial for applications with fluctuating workloads, such as AI training and data analytics. On the other hand, physical servers offer dedicated GPU resources, providing superior performance for intensive tasks that require consistent and uninterrupted computing power. This option is ideal for industries such as gaming and scientific research, where high-performance and low-latency processing are critical. The growing demand for both types reflects the diverse needs of businesses seeking to leverage cloud GPUs for various applications, driving the market's expansion.
By Deployment Model:
The deployment model segments of the global cloud GPU market include public cloud, private cloud, and hybrid cloud. The public cloud model dominates the market, driven by its cost-effectiveness, scalability, and widespread accessibility. Public cloud providers offer extensive GPU resources that can be quickly scaled up or down, catering to businesses with varying computational needs. The private cloud segment appeals to organizations requiring enhanced security and control over their data, such as financial institutions and healthcare providers. Private clouds offer dedicated environments that can be tailored to specific regulatory and compliance requirements. Hybrid cloud combines the benefits of both public and private clouds, providing a flexible and balanced approach. This model allows businesses to manage sensitive data in a private cloud while utilizing the public cloud for less critical workloads. The hybrid approach is gaining traction as companies seek to optimize their cloud strategies, balancing performance, security, and cost. Each deployment model addresses distinct market needs, contributing to the robust growth of the cloud GPU market.
Segments:
Based on Type
- Virtual Machines (VMs)
- Physical Servers
Based on Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
Based on End-user Industry
- Gaming
- Media and Entertainment
- Machine Learning and AI
- Healthcare
- Automotive
- Finance
- Others
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest market share in the global cloud GPU market, accounting for approximately 35% of the total market. This region's dominance can be attributed to the presence of major cloud service providers, such as Amazon Web Services (AWS), Microsoft Azure, and Google Cloud Platform, which have invested heavily in GPU-accelerated cloud computing solutions. Additionally, the region's strong adoption of cloud technologies across industries like gaming, healthcare, and artificial intelligence (AI) has fueled the demand for cloud GPU services.
Asia-Pacific
The Asia-Pacific region is a close second, with a market share of around 30%. Countries like China, Japan, and India have witnessed a surge in cloud GPU adoption, driven by the rapid digitalization of various sectors and the growing emphasis on advanced computing capabilities. The region's thriving gaming industry, coupled with the increasing adoption of AI and machine learning technologies across various domains, has propelled the demand for cloud GPU solutions.
Key Player Analysis
- Amazon Web Services (AWS)
- Microsoft Azure
- Google Cloud Platform (GCP)
- NVIDIA Cloud
- IBM Cloud
- Alibaba Cloud
- Oracle Cloud
- Huawei Cloud
- OVHCloud
- Scaleway
Competitive Analysis
The global cloud GPU market is highly competitive, dominated by major cloud service providers leveraging their extensive infrastructure and technological advancements. Amazon Web Services (AWS) leads the market with its broad range of GPU instances, robust ecosystem, and continuous innovation. Microsoft Azure follows closely, offering integrated GPU solutions with strong support for enterprise applications and AI development. Google Cloud Platform (GCP) excels in AI and machine learning capabilities, benefiting from Google's expertise in these areas. NVIDIA Cloud stands out with its specialized GPU offerings, catering particularly to AI and deep learning applications. IBM Cloud and Oracle Cloud provide robust GPU solutions tailored for enterprise clients, emphasizing security and performance. Alibaba Cloud is a key player in the Asia-Pacific region, rapidly expanding its GPU services to meet regional demand. Huawei Cloud focuses on integrating AI and big data analytics with its GPU offerings. OVHCloud and Scaleway, European providers, differentiate themselves with competitive pricing and local data sovereignty, appealing to regional customers.
Recent Developments
- In January 2024,WekaIO, Inc., the data platform for cloud & AI, announced a new partnership with NexGen Cloud Ltd., a cloud IaaS firm, to offer on-demand services of Hyperstack, a NexGen Cloud's GPUaaS platform.
- In December 2023, Yotta Infrastructure, the Indian hyperscale tier IV data center provider, announced a collaboration with NVIDIA Corporation, a pioneer of GPU-accelerated computing. Through this partnership, Yotta Data Services aims to provide GPU computing infrastructure and platforms for its Shakti Cloud platform.
- In April 2023, CoreWeave, a NYC-based startup, raised USD 221 million in Series B funding led by Magnetar Capital. CoreWeave offers various Nvidia GPUs in the cloud for use cases, such as visual effects & rendering, AI & ML, batch processing, and pixel streaming.
- In March 2023, Lambda Labs, a cloud company offering GPUs on-demand in a public cloud, raised USD 44 million in a Series B investment round. The company is planning to deploy thousands of Nvidia's latest H100 GPUs with high-speed network interconnects. Lambda Labs has data centers in San Francisco, Texas, California, and Allen.
Market Concentration & Characteristics
The global cloud GPU market is characterized by a high level of concentration, with a few dominant players such as Amazon Web Services (AWS), Microsoft Azure, and Google Cloud Platform (GCP) commanding a significant share. These industry giants leverage extensive infrastructure, advanced technological capabilities, and vast financial resources to maintain their competitive edge. The market also exhibits characteristics of rapid innovation and scalability, driven by the increasing demand for high-performance computing and AI-driven applications. Smaller players like NVIDIA Cloud, IBM Cloud, and Alibaba Cloud are expanding their presence, offering specialized and regional solutions to diversify the market landscape. Despite the dominance of leading providers, the market remains dynamic, with continuous advancements in GPU technology and cloud services fostering competition and growth opportunities. This concentration ensures that customers benefit from robust, scalable, and cutting-edge GPU solutions while driving ongoing improvements and price competitiveness in the sector.
Report Coverage
The research report offers an in-depth analysis based on Type, Deployment Model, End-user Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Cloud GPU Market is expected to experience robust growth driven by the increasing adoption of AI and machine learning applications.
- Demand for cloud GPUs will rise as industries such as gaming, healthcare, and automotive seek to leverage advanced graphics processing capabilities.
- Technological advancements in GPU virtualization and cloud computing will enhance the efficiency and scalability of cloud GPU solutions.
- Integration of cloud GPUs with edge computing will become more prevalent, supporting real-time data processing and analytics.
- Enterprises will increasingly shift from on-premise to cloud-based GPU solutions to reduce infrastructure costs and improve operational flexibility.
- Cloud service providers will expand their GPU offerings, introducing new and more powerful GPU instances to meet growing customer demands.
- Security and compliance will remain critical concerns, driving the development of robust security frameworks for cloud GPU environments.
- The gaming industry will continue to be a major driver of cloud GPU adoption, with cloud gaming services gaining significant traction.
- Partnerships and collaborations between cloud providers and GPU manufacturers will accelerate innovation and the deployment of advanced GPU technologies.
- The market will see increased competition as new entrants and existing players strive to capture market share through differentiated services and competitive pricing.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rise of Artificial Intelligence (AI) and Machine Learning (ML)
The proliferation of AI and ML applications across industries such as healthcare, finance, and manufacturing is driving demand for high-performance cloud GPUs, which enable faster model training and real-time analytics that are not feasible with traditional CPUs.
Growing Adoption of Cloud Computing
Businesses are migrating workloads to the cloud to benefit from scalability, flexibility, and cost savings, with cloud GPUs enabling advanced analytics, rendering, and AI development without the need for expensive on-premises infrastructure.
Demand for High-Performance Computing (HPC)
Industries like scientific research, weather forecasting, and engineering simulations require significant computational power, and cloud GPUs provide on-demand, scalable resources that accelerate complex simulations and reduce time-to-insight.
Advancements in GPU Technology
Continuous improvements in GPU performance, efficiency, and virtualization make cloud GPUs more attractive for a wider range of applications, supporting the growing complexity and volume of data-driven tasks.
Shift Towards GPU as a Service (GPUaaS)
The adoption of GPUaaS models allows organizations to dynamically scale GPU resources based on workload requirements, optimizing operational costs and enabling rapid innovation in fields such as AI, big data analytics, and media production.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Cloud GPU Market?
What factors are driving the growth of the Global Cloud GPU Market?
What are the key segments within the Global Cloud GPU Market?
What are some challenges faced by the Global Cloud GPU Market?
Who are the major players in the Global Cloud GPU Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Virtual Machines (VMs)
- 1.2.2 Physical Servers
- 1.3 By Deployment Model
- 1.3.1 Public Cloud
- 1.3.2 Private Cloud
- 1.3.3 Hybrid Cloud
- 1.4 By End-user Industry
- 1.4.1 Gaming
- 1.4.2 Media and Entertainment
- 1.4.3 Machine Learning and AI
- 1.4.4 Healthcare
- 1.4.5 Automotive
- 1.4.6 Finance
- 1.4.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 3,171.85 million → 2032: USD 47,240.73 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cloud GPU Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cloud GPU Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cloud GPU Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cloud GPU Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cloud GPU Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cloud GPU Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cloud GPU Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cloud GPU Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 3,171.85 million → 2032: USD 47,240.73 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cloud GPU Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Virtual Machines (VMs)
- 12.3.7.2 Physical Servers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment Model - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Public Cloud
- 12.4.7.2 Private Cloud
- 12.4.7.3 Hybrid Cloud
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-user Industry - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Gaming
- 12.5.7.2 Media and Entertainment
- 12.5.7.3 Machine Learning and AI
- 12.5.7.4 Healthcare
- 12.5.7.5 Automotive
- 12.5.7.6 Finance
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cloud GPU End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cloud GPU Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cloud GPU Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cloud GPU Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amazon Web Services (AWS)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Microsoft Azure
- 18.4 Google Cloud Platform (GCP)
- 18.5 NVIDIA Cloud
- 18.6 IBM Cloud
- 18.7 Alibaba Cloud
- 18.8 Oracle Cloud
- 18.9 Huawei Cloud
- 18.10 OVHCloud
- 18.11 Scaleway
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

